
VA Entitlement
Apply — soft pull only Book a 15-Minute Call
✓ Soft credit pull only. Applying won’t affect your credit score.
- My team reviews your application as soon as it comes in.
- If you qualify, you get a pre-approval letter and a full itemized estimate.
- If you’re not there yet, you get a clear plan to get ready.
Understanding VA Entitlement for Texas Veterans
When understanding how to read your certificate of eligibility, you will need to know what the VA county loan limit is in Texas. For 2026 the county loan limit is $832,750. What this means is if you have an existing VA home loan then you would be able to purchase another home but may have a down payment required. Contact us to learn what your COE means for you and if you would or would not have a down payment needed.
Run your numbers: the VA entitlement calculator shows your remaining entitlement and how much you can borrow in Texas with $0 down.
What is VA Entitlement?
VA entitlement refers to the amount the Department of Veterans Affairs (VA) guarantees for each veteran on a home loan, minimizing the VA lender‘s risk and often eliminating the need for a down payment. There are two types of entitlement: basic and second-tier (or bonus) entitlement, providing flexibility for veterans who wish to purchase a home after using some or all of their initial entitlement.
Basic Entitlement
In Texas, as elsewhere, basic entitlement is set at $36,000, with the VA guaranteeing 25% of the home loan amount. With full entitlement there is no VA loan limit. The county limit is used only when part of your entitlement is already in use.
Second-Tier Entitlement
Second-tier entitlement becomes relevant when a Texas veteran wants to purchase another home without fully restoring their initial entitlement, possibly because they haven’t sold their first home or have used their entitlement on a previous property that resulted in a foreclosure or short sale.
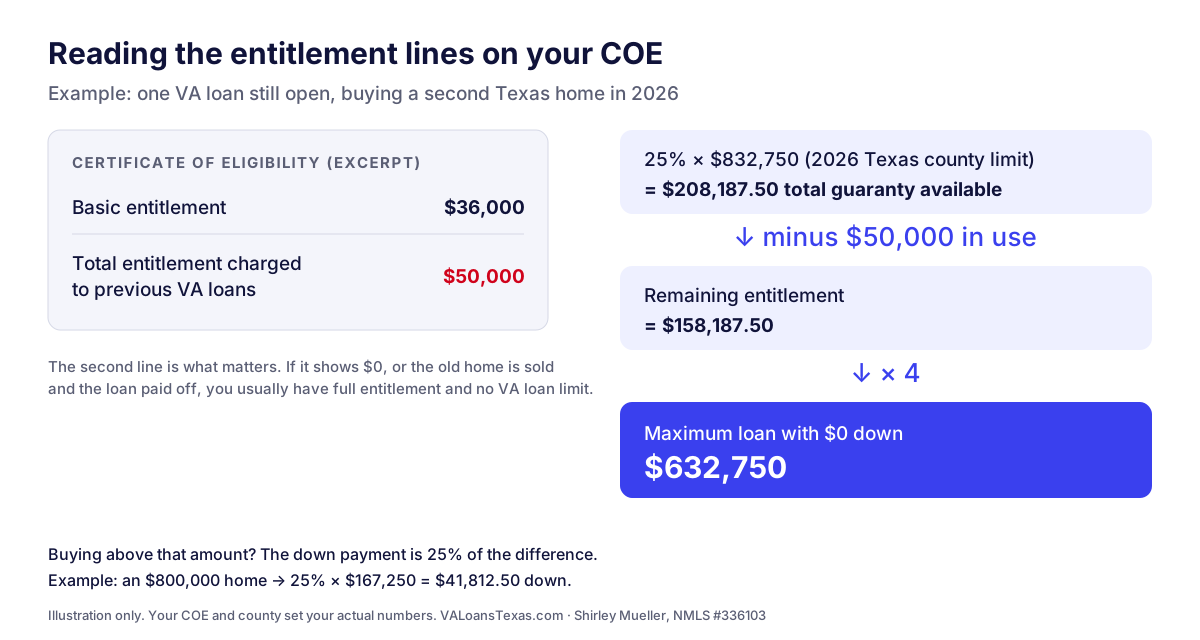
Calculating Second-Tier Entitlement in Texas
With the 2026 county loan limit in Texas set at $832,750, veterans have substantial leeway to purchase higher-priced homes. Here’s how to calculate your second-tier entitlement and the associated down payment:
- Determine the Total VA Guarantee: 25% of the county loan limit ($832,750), equating to $208,187.50, represents the total entitlement available to you.
- Subtract Used Entitlement: If you have previously used a portion of your entitlement, subtract that amount from the total entitlement. For instance, if you’ve used $50,000, you have $158,187.50 remaining.
- Calculate Maximum Loan Without Down Payment: Multiply your remaining entitlement by 4. Using the example above, this would be $632,750.
- Down Payment for Higher-Priced Homes: If the purchase price of your new Texas home exceeds this amount, you’re required to make a down payment of 25% of the difference between the purchase price and your maximum loan amount.
Example for Texas Veterans
Let’s say you’re a Texas veteran looking to purchase a home priced at $800,000, and you have $158,187.50 of entitlement remaining:
- Maximum Loan Without Down Payment: $632,750
- Home Purchase Price: $800,000
- Difference: $167,250
- Required Down Payment: 25% of $167,250 = $41,812.50
This calculation shows how veterans with remaining entitlement can buy above their zero-down amount (see VA loan limits) with a relatively modest down payment.
Key Takeaways for Texas Veterans
Understanding your VA entitlement and how to maximize it for home purchases in Texas is important. Whether you’re a first-time homebuyer or looking to purchase another property, the VA loan program provides a way to homeownership with favorable terms. By understanding your entitlement and the calculation process for second-tier entitlement, you can make informed decisions that to achieve your goals.
For personalized assistance contact us and we can help you figure out solutions to your needs.
Questions, or want a call back?
My team will be in touch soon. No cost or obligation.