

VA appraisal timeline is 7 business days for some counties and 10 business days for others. The timeline begins on the first business day after assignment. Weekends and federal holidays are not included. This is the VA’s target for completing the appraiser’s work, not a guarantee of the total time between the lender ordering the appraisal and the borrower receiving the Notice of Value.
Counties like Bell, Bexar, Collin, Comal, Coryell, Dallas, Guadalupe, Harris, Montgomery, Tarrant and Williamson have 7 business days va appraisal timeline and all the rest of the counties have 10 business days for va appraisal timeline.
The current VA Appraisal Fees and Timeliness Table became effective May 1, 2026. Assignment delays, property-access problems, appraisal corrections, repairs, Tidewater review and lender or VA review can extend the total timeline.
Plan for approximately 30 to 45 calendar days from an accepted purchase contract to closing on a VA purchase loan in Texas. Your lender’s processing speed, appraisal scheduling, documentation, and required repairs affect the actual timeline.
VA Appraisal Fees and Turn Times in Texas: 2026
| Texas area | Counties | Single-family and condominium fee | Manufactured-home fee | 2–4 unit fee | Target turnaround time |
|---|---|---|---|---|---|
| Seven-day counties | Bell, Bexar, Collin, Comal, Coryell, Dallas, Guadalupe, Harris, Montgomery, Tarrant and Williamson |
$800 | $850 | $925 | 7 business days |
| Standard Texas counties | Most other Texas counties, excluding the higher-fee counties listed below |
$775 | $825 | $900 | 10 business days |
| Higher-fee counties | Andrews, Borden, Cochran, El Paso, Foard, Hidalgo, Howard, Kenedy, Kent, King, Leon, Loving, Maverick, Reeves, Roberts, Stonewall, Throckmorton, Val Verde and Winkler |
$900 | $950 | $1,050 | 10 business days |
These are the VA-published appraisal fees and timeliness targets effective May 1, 2026. VA may temporarily adjust fees or turn times when market demand, appraiser availability or other local conditions require a change.
Does Texas Require a VA Appraisal to Be Completed Within 7 Days?
No. There is not a statewide Texas rule requiring every VA appraisal or VA loan to be completed within seven days.
The 7-business-day period comes from the Department of Veterans Affairs’ appraisal timeliness schedule. It applies only to VA appraisal assignments in the 11 Texas counties listed above.
For most other Texas counties, the published VA appraisal timeliness is 10 business days.
The VA describes these timeframes as requirements for VA-specific appraisal assignments and expected service levels for VA fee panel appraisers. They should not be confused with a deadline for the entire mortgage transaction.
The 7 or 10 business days does not mean all of the following must be completed during that period. The following processes may continue after appraisal itself has been completed:
- Loan underwriting
- Required property repairs
- Reinspection
- Appraisal review
- Notice of Value
- Tidewater
- Reconsideration of Value
- Title work
- Final loan approval
- Closing
Those parts of the loan can continue after the appraisal itself has been completed.
Does the 7-Day VA Appraisal Rule Mean You Can Close in 7 Days?
No.
This is one of the most important points for Texas VA borrowers to understand.
The 7-business-day appraisal requirement in certain Texas counties applies to the appraisal assignment. It is not a seven-day requirement for the entire VA home loan.
Even after the appraisal is completed, the lender may still need to finish:
- Appraisal review
- Underwriting
- Required repairs
- Reinspection
- Title work
- Homeowners insurance
- Final document review
- Closing disclosures
- Final loan approval
A property can therefore have a 7-business-day VA appraisal timeline while the full VA loan takes longer to close.
What Is the VA Loan Closing Timeline in Texas?
| Estimated Timing | Closing Stage | What Happens? | What Should the Buyer Do? |
|---|---|---|---|
| Days 1–5 | Contract, eligibility, and appraisal order | The lender receives the signed purchase contract, verifies the Certificate of Eligibility (COE), collects financial documents, and orders the VA appraisal. Earnest money and any option fee are delivered according to the contract deadlines. | Submit requested income and asset documents promptly. Confirm payment deadlines with your agent and arrange a home inspection within your negotiated option period. |
| Days 6–15 | Appraisal, processing, and initial underwriting | The appraiser evaluates the property’s value and VA Minimum Property Requirements (MPRs). Underwriting reviews the borrower’s credit, income, assets, and loan eligibility. Texas appraisal completion targets are 7 or 10 business days, depending on the county, starting the first business day after assignment. | Respond to requests for additional documents and discuss inspection findings with your agent before your contractual option period expires. A VA appraisal does not replace a home inspection. |
| Days 16–25 | Underwriting conditions and required repairs | The lender reviews the appraisal and outstanding underwriting conditions. Any required MPR repairs are addressed, with completion verification when required. Title and applicable HOA documents are reviewed as processing continues. | Provide outstanding paperwork, coordinate agreed repairs, and confirm whether a follow-up property inspection or repair verification is needed. |
| Around Days 26–30 | Final approval and Closing Disclosure | Once approval requirements are satisfied, the lender issues clear-to-close authorization. The Closing Disclosure confirms loan terms, payments, closing costs, and cash to close. The buyer must receive it at least three business days before closing. | Review the disclosure, raise any questions with your lender, confirm closing arrangements, and schedule the final walkthrough. |
| Around Days 30–45 | Signing, funding, and recording | The buyer signs the closing documents and provides any required closing funds. The lender authorizes funding, and the title company handles disbursement and recording with the appropriate county. | Bring the identification requested by the title company. Confirm funding and the contract’s possession terms before arranging your move. |
What Can Delay a VA Loan Closing in Texas?
| Potential Delay | How Can It Affect Closing? | What Can Help? |
|---|---|---|
| Appraisal scheduling or backlogs | Limited appraiser availability, property access problems, or heavy demand can extend completion beyond the county’s published target. | Have the lender order the appraisal promptly and ensure the seller provides timely property access. |
| Required property repairs | Repairs needed to satisfy VA property requirements can add time for contractor scheduling, completion, and verification. | Agree on repair responsibilities early and confirm the lender’s requirements for documenting completion. |
| Appraisal below the purchase price | A value shortfall may require price negotiations, additional buyer funds, or a reconsideration of value. | Discuss available options promptly with your lender and real estate agent. |
| Missing underwriting documents | Outstanding income records, asset statements, employment verification, or eligibility documents can hold up final approval. | Submit complete documents and respond quickly to follow-up requests. |
| HOA or title paperwork | Missing resale certificates, unresolved liens, or other title issues can delay closing preparation. | Request applicable HOA documents early and work with the title company to resolve outstanding issues. |
| Closing Disclosure timing | Late receipt can move the closing date. Certain significant loan changes require a corrected disclosure and a new three-business-day waiting period. | Review the disclosure immediately and confirm the earliest permitted closing date with your lender. |
Timing note: The overall schedule uses calendar days. VA appraisal targets use business days and exclude weekends and federal holidays. The Closing Disclosure waiting period uses a different business-day definition, generally including Saturdays but excluding Sundays and federal legal holidays. Confirm your specific deadlines with your lender.
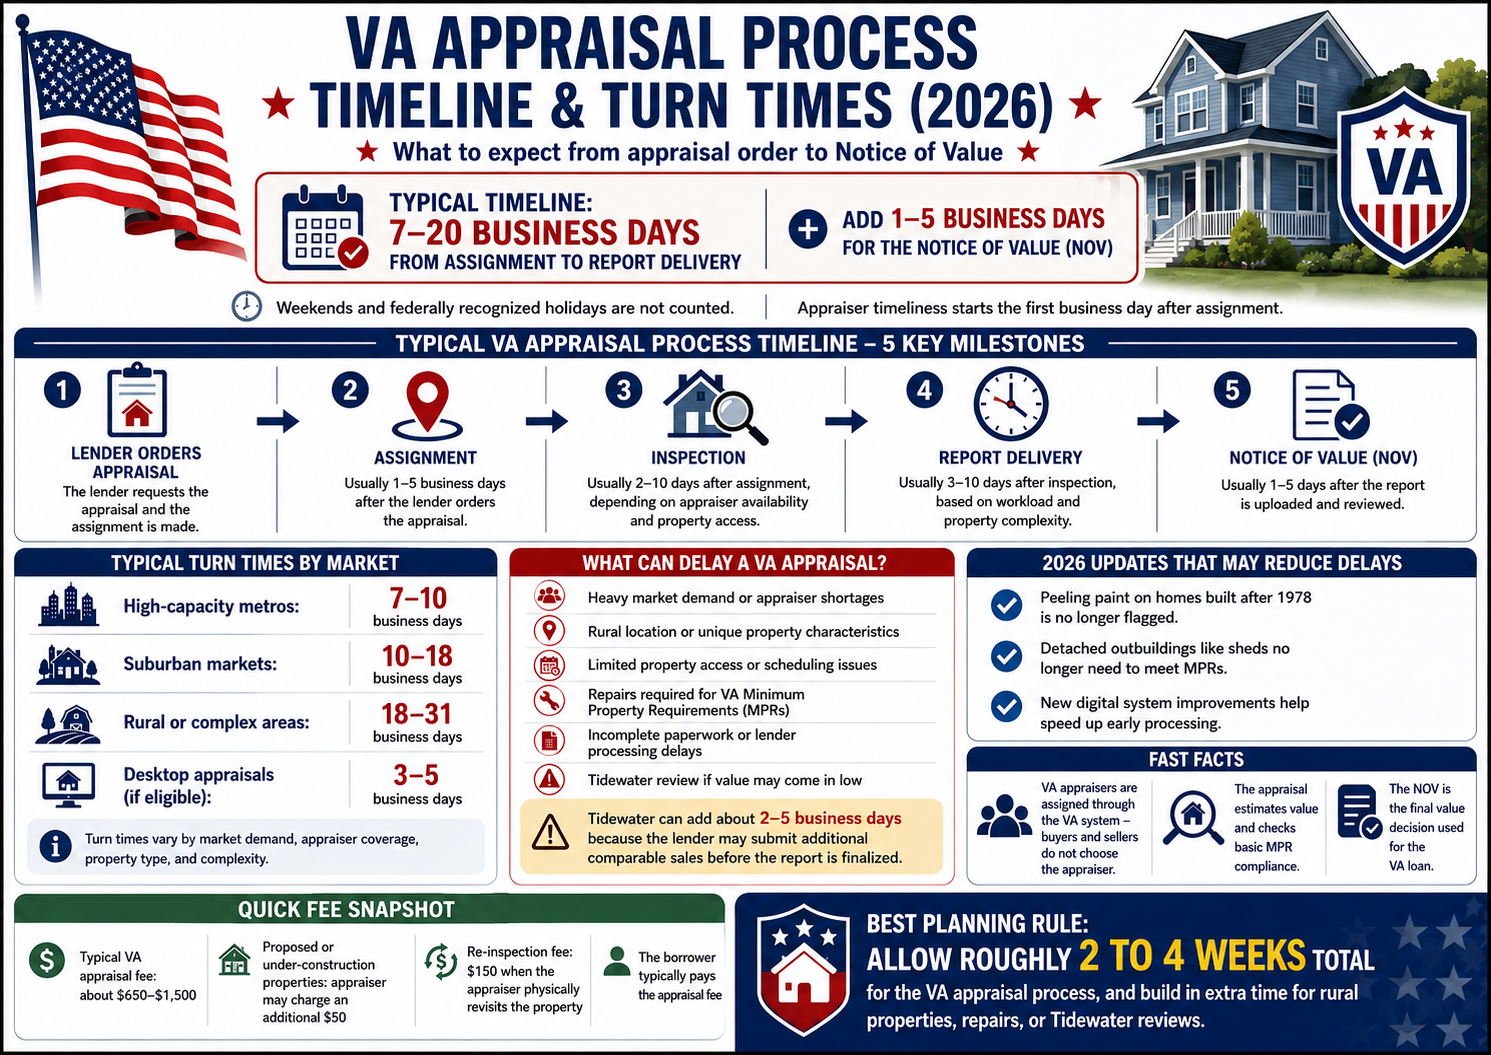
What Is the VA Appraisal Process Timeline?
The VA appraisal process timeline includes more than the appraiser’s visit to the property.
Here is what usually happens.
Step 1: The Lender Requests the VA Appraisal
After the home is under contract and the VA loan process has started, the lender requests the appraisal.
The borrower does not select the VA appraiser.
Step 2: The Appraisal Is Assigned
The request is assigned to a VA fee appraiser.
This is the date borrowers should pay attention to when checking the VA loan appraisal timeline.
The official VA timeliness period starts on the first business day after this assignment date.
Step 3: The Appraiser Schedules Access to the Property
The appraiser arranges a time to visit the property.
How quickly this happens can depend on access to the home, the seller’s schedule, the appraiser’s workload, and local conditions.
Step 4: The Appraiser Visits the Property
The appraiser observes the property and collects the information needed for the appraisal.
The appraiser also considers whether the property meets the applicable VA property requirements.
The appraisal is not complete simply because the property visit has taken place.
Step 5: The Appraiser Completes the Valuation
After visiting the home, the appraiser still needs to complete the report.
This may involve reviewing comparable properties, market information, property details, and other information needed to develop the opinion of value.
Step 6: The Appraisal Is Submitted
Once the report is completed, it is submitted through the VA appraisal system.
The appraisal then goes through the applicable review process before the Notice of Value is issued.
Step 7: Any Appraisal Issues Are Addressed
If the appraisal supports the transaction and no property conditions need to be resolved, the loan can continue through the remaining steps.
Additional time may be needed when there are:
- Required repairs
- Appraisal corrections
- Questions about property condition
- Value issues
- Tidewater
- Reconsideration of Value
- Reinspection requirements
This is why the VA appraisal timeline and the VA loan closing timeline should not be treated as the same thing.
Current VA Appraisal Timelines in Texas
| Texas Location | Published VA Appraisal Timeliness |
| Most Texas counties | 10 business days |
| Bell County | 7 business days |
| Bexar County | 7 business days |
| Collin County | 7 business days |
| Comal County | 7 business days |
| Coryell County | 7 business days |
| Dallas County | 7 business days |
| Guadalupe County | 7 business days |
| Harris County | 7 business days |
| Montgomery County | 7 business days |
| Tarrant County | 7 business days |
| Williamson County | 7 business days |
Does the VA Appraisal Timeline Start When the Lender Orders It?
No. The official VA timeliness target starts on the first business day after the appraisal is assigned to an appraiser, not necessarily on the day the lender submits the appraisal request.
This distinction is important because the total borrower experience can include several separate stages:
1. The lender submits the appraisal request.
2. The appraisal is assigned to an appraiser.
3. The official county turn-time clock begins on the next business day.
4. The appraiser schedules access and visits the property.
5. The appraiser researches comparable sales and uploads the report.
6. The lender’s VA-authorized Staff Appraisal Reviewer reviews the report and normally issues the Notice of Value in LAPP cases.
7. VA reviews and issues the Notice of Value in non-LAPP cases.
8. Any appraisal conditions, repairs or valuation questions are resolved before final loan approval.
Therefore, a county with a seven-business-day target does not necessarily produce a Notice of Value exactly seven days after the lender orders the appraisal.
What Are the VA Appraisal Requirements?
A VA appraisal is part of the VA homebuying process.
The lender requests a VA-approved appraiser to evaluate the property. The appraisal has two important purposes:
- To provide an opinion of the property’s value.
- To determine whether the property meets the VA’s applicable Minimum Property Requirements, commonly called MPRs.
The appraiser is not performing the same type of detailed examination that a home inspector performs.
The VA appraisal focuses on the property’s value and whether it meets the property requirements that apply to a VA-backed loan.
If the appraiser identifies a property condition that must be addressed, repairs or additional documentation may be required before the loan can continue.
Did the VA Appraisal Requirements Change in 2026?
Yes.
VA updated Chapter 12 of its Lenders Handbook, which covers Minimum Property Requirements. Those changes took effect on May 1, 2026.
The changes included updates to several property requirements that had been contributing to appraisal delays and added costs. VA specifically reported changes involving radon requirements, properties built before and after 1978, detached improvements, certain heating requirements, and other appraisal guidance.
This is separate from the 7-business-day appraisal timeline.
The 2026 MPR updates changed some property requirements, while the VA appraisal fee and timeliness schedule sets the number of business days allowed for appraisal assignments.
They are related to the appraisal process, but they are not the same rule.
How Long After the Property Visit Does the VA Appraisal Report Come Back?
VA does not publish a separate nationwide deadline measured from the date of the property visit. The official timeliness target is measured from the appraisal assignment date.
A property visit completed early in the county’s turn-time window may still require additional time for comparable-sales research, report preparation and quality review. When asking for an update, request the assignment date rather than relying only on the inspection date.
How Long Does a VA Appraisal Take to Come Back After the Property Visit?
There is no separate VA rule saying the appraisal report must be returned within a certain number of days after the appraiser physically visits the home.
The VA’s published timeline is based on the appraisal assignment date. After leaving the property, the appraiser may still need to:
- Review comparable sales
- Confirm property and market information
- Complete the valuation
- Document property conditions
- Finish the appraisal report
- Upload the appraisal
So, if the appraiser visited the property two days ago, that does not necessarily mean the report is late.
The better question to ask the lender is:
“What date was the VA appraisal assigned, and what is the VA timeliness requirement for this county?”
That gives you a much clearer idea of where the appraisal stands.
How Can I Check the Status of My VA Appraisal?
The most reliable way to check the status is through your loan officer or lender. The lender and its VA-authorized reviewer can review the appraisal record in WebLGY.
Ask your lender these five questions:
1. On what date was the appraisal ordered?
2. On what date was it assigned to the appraiser?
3. Has the appraiser completed the property visit?
4. Has the appraisal report been uploaded?
5. Has the Notice of Value been issued?
These questions identify whether the delay is occurring before assignment, during the appraiser’s work or during report review.
What Should I Do If the VA Appraisal Is Late?
First, compare the appraisal assignment date with the official target for the property’s county. Remember to exclude weekends and federal holidays.
When the county target has passed:
1. Ask your lender whether the appraiser has provided a delay reason or revised delivery date.
2. Confirm whether the report is still being prepared or has already been uploaded for review.
3. Ask whether the Staff Appraisal Reviewer needs a correction or additional information.
4. Confirm whether Tidewater, repairs or a reconsideration of value is affecting the timeline.
5. Ask the lender to escalate the issue through its VA appraisal channel when the report remains overdue without a clear explanation.
Borrowers should work through their lender rather than contacting the appraiser to discuss or influence the property value.
What Can Delay a VA Appraisal?
| Cause of delay | How it affects the timeline |
| Difficulty accessing the property | The appraiser cannot complete the site visit until access is arranged |
| Rural or unique property | Finding appropriate comparable sales may require additional research |
| Limited appraiser availability | Assignment may take longer in high-demand or remote markets |
| Minimum Property Requirement concerns | The report may identify repairs that must be resolved |
| Tidewater process | The lender and agents may need to submit additional comparable-sales information |
| Appraisal corrections | The reviewer may return the report for clarification or revision |
| Reinspection | The appraiser may need to revisit the property after required repairs |
| Reconsideration of value | Additional sales evidence and review may be required before the value is finalized |
Avoid promising an exact number of additional days for these situations because the delay depends on the property, appraiser availability and the issue being resolved.
Is a VA Appraisal the Same as a Home Inspection?
No.
A VA appraisal and a home inspection are two separate things.
A VA-approved appraiser provides an opinion of the home’s value and checks the property against applicable VA Minimum Property Requirements.
A home inspection gives the buyer a more detailed look at the physical condition of the property.
The VA specifically recommends that buyers get a home inspection and states that a VA appraisal is not the same as an inspection.
A home inspector may look more closely at areas such as:
- Roof
- Foundation
- Electrical system
- Plumbing
- Heating and cooling systems
- Appliances
- Interior and exterior condition
- Signs of water damage or other problems
An appraisal should not be used as a replacement for a home inspection.
How Long After the VA Appraisal Can You Close?
There is no single VA rule stating that every loan must close a fixed number of days after the appraisal.
After the appraisal and Notice of Value are complete, the lender may still need to:
- Clear appraisal or repair conditions
- Complete underwriting
- Verify title and homeowners insurance
- Review updated financial documents
- Confirm that all lender conditions are satisfied
- Issue the Closing Disclosure
- Complete the required Closing Disclosure waiting period
Federal rules generally require the borrower to receive the Closing Disclosure at least three business days before closing.
A clean appraisal with no repairs or value dispute can keep the loan moving efficiently, but the actual closing date depends on the status of the entire mortgage file.
Frequently Asked Questions: VA Appraisal Turn Times
How many days does a VA appraiser have to complete an appraisal in Texas?
The official target is seven or 10 business days after assignment, depending on the Texas county. Weekends and federal holidays are excluded.
Which Texas counties have a seven-business-day VA appraisal target?
Bell, Bexar, Collin, Comal, Coryell, Dallas, Guadalupe, Harris, Montgomery, Tarrant and Williamson counties currently have a seven-business-day target.
Is the VA appraisal deadline counted from the order date?
No. The VA timetable begins on the first business day after the appraisal is assigned.
Can a borrower track a VA appraisal online?
Borrowers should request the status from their lender. The lender and its VA-authorized reviewer track appraisal activity through VA systems such as WebLGY.
Who issues the Notice of Value?
In LAPP cases, the lender’s VA-authorized Staff Appraisal Reviewer normally reviews the appraisal and issues the Notice of Value. VA performs this function in non-LAPP cases.
Does underwriting stop while the appraisal is pending?
Other parts of the mortgage process may continue while the appraisal is pending. However, the final appraisal, Notice of Value and any related conditions must be resolved before final approval and closing.
Does a VA appraisal replace a home inspection?
No. A VA appraisal evaluates value and applicable property requirements for the loan. A home inspection is a separate evaluation of the property’s physical condition.
What happens when repairs are required?
The lender will explain which repairs must be completed and whether a reinspection or other documentation is needed before the appraisal condition can be cleared.