
VA Construction Loan FAQs
Check Your Eligibility Book a 15-Minute Call
✓ Soft credit pull only. Applying won’t affect your credit score.
- My team reviews your application as soon as it comes in.
- If you qualify, you get a pre-approval letter and a full itemized estimate.
- If you’re not there yet, you get a clear plan to get ready.
General VA Construction loan questions
What is a VA Construction Loan?
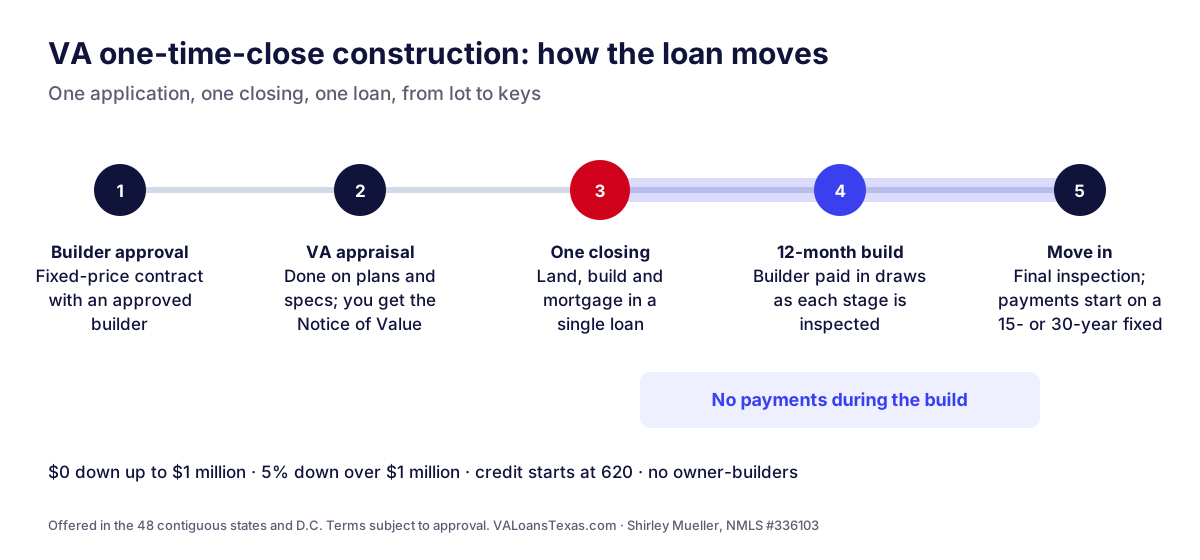
A VA Construction Loan is a type of mortgage financing that allows veterans to build their home using their VA home loan benefit and obtain all the benefits of a normal VA loan (no down payment, no private mortgage insurance, competitive interest rates, flexible credit). This is a one-time close allowing you to close on the construction and land (if not already owned) in one closing. Once the closing has been completed, then construction begins. Once the home is built, the loan turns into a permanent VA loan and there is not a second closing.
Who Offers VA Construction Loans?
We have found that a lot of lenders do not offer VA construction loans. Here at CrossCountry Mortgage, we are able to offer VA construction loans not only in Texas but in the 48 contiguous states and D.C.
Is a down payment required on a VA Construction Loan?
No down payment is required under the VA guidelines. However, the lender that is offering this loan can require a down payment. Here at CrossCountry Mortgage, we require a 5% down payment if the loan amount is over $1 million. Any loan amount up to $1 million has no down payment.
What is your max loan amount on a VA Construction Loan?
Assuming you do not have an existing VA loan, we are able to lend up to $2 million on a VA construction loan. Loans over $1 million require 5% down.
How do I apply for a VA Construction Loan with your company?
You would submit your application online. At this stage we only do a “soft” credit pull which will not impact your credit. Once we receive your application, we will contact you to go over it and then will request the items needed to understand how much you would be qualified for under the VA Construction Loan program. Once you understand that, we issue a pre-approval letter, provide an estimate and wait for you to find your builder and your land if you don’t own that already.
Builder, Construction, Property and Land Questions
Can I finance the land into the construction loan?
Yes, we would consolidate the land loan into your construction loan. If you do not own the land yet, the VA construction loan would include the land purchase in the closing.
Can I subdivide the parcel of land into separate parcels?
Each scenario would need an evaluation. We would need to evaluate this to confirm this specific need.
How does your company approve my builder?
The builder would complete our builder package as well as provide 3 projects they have worked on in the past. Our team and the builder will work together to gather all the necessary documents.
Does the Builder need to have a VA ID Number if this is a VA Construction Loan?
No, as of 2025, the VA no longer requires the builder to become VA approved or issued a VA builder ID number.
What property types are allowed with a VA Construction Loan?
Single-family homes, 2–4 unit homes (you live in one unit), barndominiums, modular homes, log homes and new manufactured homes (primary residence only). Attached homes, co-ops and container homes aren’t eligible.
Are Container Homes allowed?
No, we do not finance container homes on any construction loan products.
Are ADU’s or guest homes allowed?
Yes, but they must be built at the same time as the primary structure. ADU’s are not allowed with manufactured homes.
Can I build the home myself and not use a builder?
No, we do not allow you to be your own builder. You would have to select a builder and then we would need to approve your builder.
If construction has already begun, can I do a VA Construction Loan?
Only the lot prep can be started, and no construction or structural work of any kind can be started.
If the home doesn't appraise for the total price, what are my options?
We would need to review and see what is needed to meet the VA guidelines. If needed, you can adjust the construction contract or put additional money down in order to meet the VA appraisal requirements.
Closing Cost, Fees and Mortgage Payment Questions
What lender fees are charged on one-time close VA Construction Loans?
We only charge a construction management fee, and it is a tiered fee schedule based on the loan amount. This is a fee that includes everything associated with the construction.
Can I roll in all my closing costs into the VA Construction Loan?
Yes, depending on how much equity you have you would be able to cover your closing costs in your loan. The VA appraisal that is ordered during the loan process will show us how much equity is available.
Do I have a mortgage payment during construction?
No, on VA construction loans there will be no payment made during construction. Instead, an Interest Reserve amount is added to the budget/cost to build. Any interest reserve that isn’t used becomes a principal reduction when the loan is modified after the build.
Is there a contingency fee required?
Yes, there is a 2% contingency fee required that is a reserve credit line established in the budget/cost to build and can be used during construction period for items that are added after the loan has closed. If the entire amount of the contingency is not used, it will be a principal reduction to the loan amount at the time of modification.
What other closing costs are required?
Third party fees. This is your appraisal, credit report, flood certificate and all title fees. We do not collect escrows during construction. You would be responsible for the taxes during construction period.
What is my interest rate on a VA Construction Loan?
To quote you an interest rate we would need a loan application from you. This only involves a “soft” credit pull and will allow us to give you an accurate rate quote. We will also be able to provide you a detailed estimate to give you an idea of all costs and fees involved.
VA Construction Loan Veteran Qualification Questions
What is your minimum credit score on a VA Construction Loan?
VA construction loans start at a 620 minimum credit score, and larger loan amounts may need a higher score. Loans over $1,000,000 also require 5% down.
If I own a home already, would I have to qualify with my current mortgage payment?
Yes, the one-time close VA construction loan closes upfront as if the house were already built (like an existing purchase transaction). You would need to qualify with both house payments unless the home is sold prior to your construction loan closing or you intend on renting your home after your home is built.
Can I exclude my current house payment during construction if I rent my home?
Possibly. If you plan to rent out your current home once the new one is finished, the rent can be used to offset that mortgage payment, following VA guidelines. That usually takes a signed lease, and VA may also look for cash reserves or past landlord experience. My team will tell you exactly what’s needed for your situation, so you can stay in your home while the new one is built.
Questions, or want a call back?
My team will be in touch soon. No cost or obligation.